Lévy distribution
|
Probability density function  | |||
|
Cumulative distribution function  | |||
| Parameters | location; scale | ||
|---|---|---|---|
| Support | |||
| CDF | |||
| Quantile | |||
| Mean | |||
| Median | |||
| Mode | |||
| Variance | |||
| Skewness | undefined | ||
| Kurtosis | undefined | ||
| Entropy |
where is the Euler-Mascheroni constant | ||
| MGF | undefined | ||
| CF | |||
In probability theory and statistics, the Lévy distribution, named after Paul Lévy, is a continuous probability distribution for a non-negative random variable. In spectroscopy, this distribution, with frequency as the dependent variable, is known as a van der Waals profile.[note 1] It is a special case of the inverse-gamma distribution. It is a stable distribution.
Definition
The probability density function of the Lévy distribution over the domain is
where is the location parameter, and is the scale parameter. The cumulative distribution function is
where is the complementary error function, and is the Laplace function (CDF of the standard normal distribution). The shift parameter has the effect of shifting the curve to the right by an amount and changing the support to the interval [, ). Like all stable distributions, the Lévy distribution has a standard form f(x; 0, 1) which has the following property:
where y is defined as
The characteristic function of the Lévy distribution is given by
Note that the characteristic function can also be written in the same form used for the stable distribution with and :
Assuming , the nth moment of the unshifted Lévy distribution is formally defined by
which diverges for all , so that the integer moments of the Lévy distribution do not exist (only some fractional moments).
The moment-generating function would be formally defined by
however, this diverges for and is therefore not defined on an interval around zero, so the moment-generating function is actually undefined.
Like all stable distributions except the normal distribution, the wing of the probability density function exhibits heavy tail behavior falling off according to a power law:
- as
which shows that the Lévy distribution is not just heavy-tailed but also fat-tailed. This is illustrated in the diagram below, in which the probability density functions for various values of c and are plotted on a log–log plot:
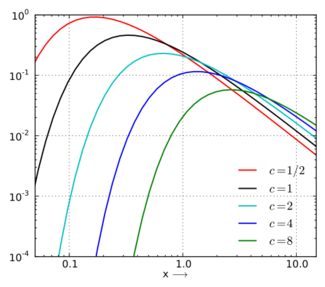
Probability density function for the Lévy distribution on a log–log plot

The standard Lévy distribution satisfies the condition of being stable:
where are independent standard Lévy-variables with
Related distributions
- If , then
- If , then (inverse gamma distribution). Here, the Lévy distribution is a special case of a Pearson type V distribution.
- If (normal distribution), then
- If , then .
- If , then (stable distribution).
- If , then (scaled-inverse-chi-squared distribution).
- If , then (folded normal distribution).
Random-sample generation
Random samples from the Lévy distribution can be generated using inverse transform sampling. Given a random variate U drawn from the uniform distribution on the unit interval (0, 1], the variate X given by[1]
is Lévy-distributed with location and scale . Here is the cumulative distribution function of the standard normal distribution.
Applications
- The frequency of geomagnetic reversals appears to follow a Lévy distribution
- The time of hitting a single point, at distance from the starting point, by the Brownian motion has the Lévy distribution with . (For a Brownian motion with drift, this time may follow an inverse Gaussian distribution, which has the Lévy distribution as a limit.)
- The length of the path followed by a photon in a turbid medium follows the Lévy distribution.[2]
- A Cauchy process can be defined as a Brownian motion subordinated to a process associated with a Lévy distribution.[3]
Footnotes
- ↑ "van der Waals profile" appears with lowercase "van" in almost all sources, such as: Statistical mechanics of the liquid surface by Clive Anthony Croxton, 1980, A Wiley-Interscience publication, ISBN 0-471-27663-4, ISBN 978-0-471-27663-0, [1]; and in Journal of technical physics, Volume 36, by Instytut Podstawowych Problemów Techniki (Polska Akademia Nauk), publisher: Państwowe Wydawn. Naukowe., 1995, [2]
Notes
- ↑ "The Lévy Distribution". The University of Alabama in Huntsville, Department of Mathematical Sciences. http://www.math.uah.edu/stat/special/Levy.html.
- ↑ Rogers, Geoffrey L. (2008). "Multiple path analysis of reflectance from turbid media". Journal of the Optical Society of America A 25 (11): 2879–2883. doi:10.1364/josaa.25.002879. PMID 18978870. Bibcode: 2008JOSAA..25.2879R.
- ↑ Applebaum, D.. "Lectures on Lévy processes and Stochastic calculus, Braunschweig; Lecture 2: Lévy processes". University of Sheffield. pp. 37–53. http://www.applebaum.staff.shef.ac.uk/Brauns2notes.pdf.
References
- "Information on stable distributions". https://edspace.american.edu/jpnolan/stable/. - John P. Nolan's introduction to stable distributions, some papers on stable laws, and a free program to compute stable densities, cumulative distribution functions, quantiles, estimate parameters, etc. See especially An introduction to stable distributions, Chapter 1
External links
 |  |


